
How to Invest in Fixed Income Products While Managing Risk Effectively
Fixed income products are investment securities that provide investors with regular, predetermined interest payments and the return of principal at maturity.
- Initiatives News
- 4 min read


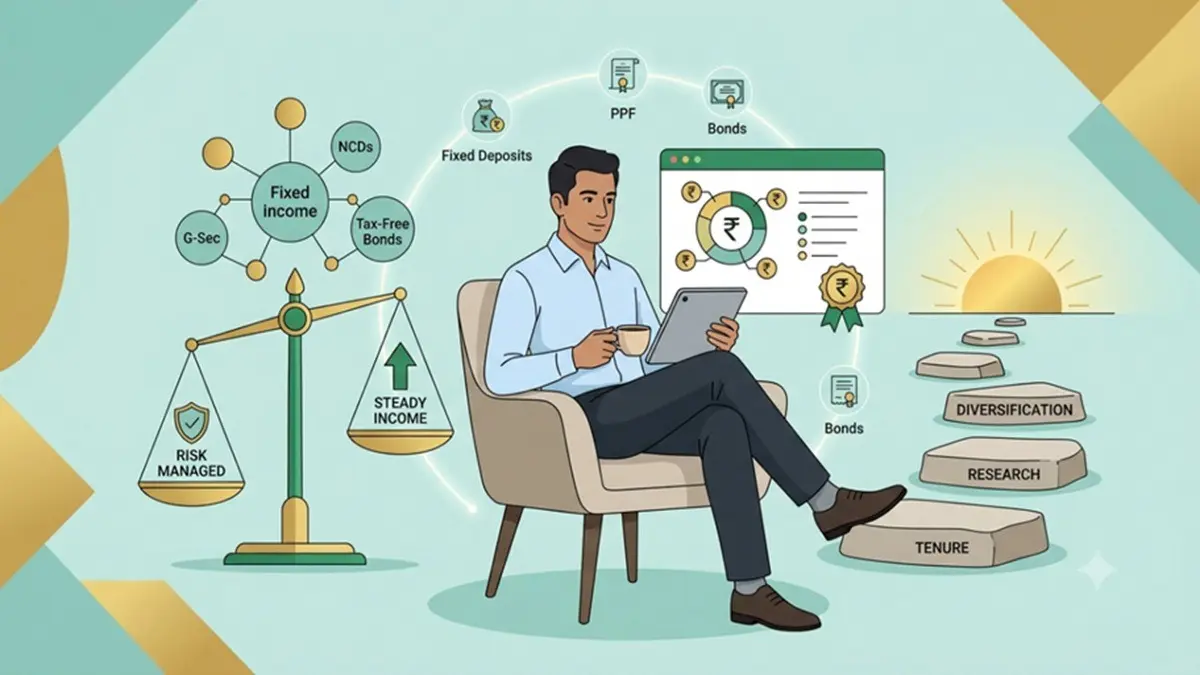
Investors looking for regular income may frequently use fixed income products. These financial instruments typically repay the principal at maturity and provide interest on a regular basis. Fixed income investments are not risk-free. Returns may be impacted by changes in interest rates, inflation, credit crises, and liquidity problems. Prior to making financial decisions, it is crucial to comprehend these risks.
Understanding Fixed Income Products
Fixed income products are investment securities that provide investors with regular, predetermined interest payments and the return of principal at maturity. Investors may invest in fixed income products as part of a diversified portfolio, depending on their financial objectives and risk considerations.
Some common fixed income products include:
- Government securities
- Corporate bonds
- Treasury bills
- Fixed deposits
- Tax-free bonds
- Certificates of deposit
- Debt mutual funds
The risk, possible return, liquidity, and investment tenure of each product vary. Before choosing any fixed income investment, investors should be aware of these characteristics.
Advertisement
Let’s now understand how you should proceed if you’re looking to invest in any fixed-income instrument. Here's what you should follow.
Assess Risks Before Investing
The degree of risk associated with each fixed-income product varies. Investors may be able to select appropriate investing options by assessing these risks.
Advertisement
Some important risks include:
- Credit Risk: The issuer might not pay back principal or interest on schedule.
- Interest Rate Risk: The market value of investments may be impacted by changes in interest rates.
- Inflation Risk: As prices rise, investment returns may lose some of their actual value.
- Liquidity Risk: Selling some instruments in the secondary market could be challenging.
Investors may be able to make better investment selections if they are aware of these risks.
Align Investment Tenure with Financial Goals
Fixed income products are available across short, medium, and long-term maturities. Selecting an appropriate tenure is an important investment consideration.
Investors may evaluate factors such as:
- Expected holding period
- Future financial commitments
- Liquidity requirements
- Income expectations
Liquidity and reinvestment risks may be better managed by aligning investment tenure with financial objectives. Investments with longer maturities could present various yield prospects. They might, however, also be more susceptible to changes in interest rates.
Monitor Interest Rate Movements
Interest rates have a direct impact on many fixed income investments. Changes in rates may affect both returns and market valuations.
When interest rates rise, existing bond prices generally decline. Bond prices may rise when interest rates decline. Investors who want to sell their bond holdings before maturity should understand how changes in interest rates may impact the exit value of their investments. Monitoring the interest rate environment may help make better portfolio decisions.
Evaluate Issuer Credit Quality
Credit quality is particularly important when investing in corporate bonds and other private debt instruments.
Before investing, investors may review:
- Credit ratings from recognised rating agencies
- Financial strength of the issuer
- Debt repayment history
- Industry-related risks
Higher-rated issuers may be considered to have lower default risk. However, no investment is completely free from risk. Assessing credit quality may help investors better understand the risks associated with a specific investment.
Diversify Across Different Fixed Income Instruments
Diversification remains an important part of risk management within fixed income portfolios. Investing across different instruments may help reduce concentration risk.
A diversified fixed income portfolio may include:
- Government securities investments
- Corporate bonds
- Fixed deposits
- Debt mutual funds
Different instruments react to market situations in different ways. Diversification may therefore aid in balancing the total risk of a portfolio. Diversification does not totally remove investment risk, while it may lower the overall portfolio risk due to underperformance of a single or few assets.
Review the Portfolio Periodically
Investment needs and market conditions may change over time. Periodic portfolio reviews may help investors maintain alignment with their financial objectives.
A review may include:
- Evaluating diversification levels
- Assessing credit exposure
- Reviewing maturity distribution
- Analysing liquidity requirements
Regular monitoring may help identify areas that require adjustment as market conditions evolve.
Conclusion
Fixed income products may provide regular income and support for portfolio diversification. They are still subject to risks including credit risk, inflation risk, interest rate risk, and liquidity risk. When investing in fixed income products, investors should carefully consider government securities investments, issuer quality, maturity profiles, and diversification options. Making well-informed investing decisions may be aided by a methodical approach to risk assessment and regular portfolio evaluations. Moreover, investors should access regulated investment platforms like Altifi to start their bond investment journey with reliable services.